- 12/09/2026
- Govind S. Jethani
- 55 Views
- 2 Likes
- Finance
How to Improve Your Credit Score in the USA?
Your credit score can have a major impact on your financial life in the USA. Lenders may use your credit score when deciding whether to approve you for a credit card, auto loan or mortgage. A higher score may also help you qualify for better interest rates and loan terms.
If your credit score is low, improving it usually takes time and consistent financial habits. There is no guaranteed overnight solution, but several practical steps can help you build a stronger credit profile.
Understand What a Credit Score Is:
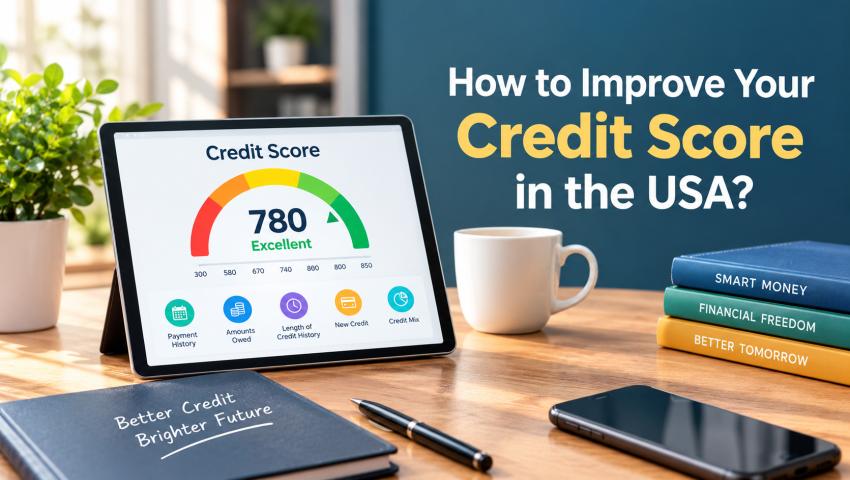
A credit score is a number calculated using information from your credit reports. There is not just one credit score because different scoring models can use different information and calculations. Most credit scores fall within a range of 300 to 850.
For example, FICO Scores consider five major categories: payment history, amounts owed, length of credit history, new credit and credit mix. Payment history and amounts owed are particularly important in the FICO scoring model.
Understanding these factors can help you make better decisions about your credit.
1. Pay Your Bills on Time:
One of the most important things you can do to improve your credit score is to pay your bills on time.
Payment history is a major factor in credit scoring. Even a missed or late payment can negatively affect your credit history, particularly when it is recent or severe.
Consider setting up automatic payments or electronic reminders for credit cards, personal loans, auto loans and other accounts.
If you have already missed payments, focus on getting your accounts current and maintaining on-time payments going forward.
2. Keep Your Credit Card Balances Low:
Another important factor is how much of your available credit you are using. This is commonly called credit utilization.
For example, if your credit card limit is $10,000 and your balance is $3,000, your utilization is 30%.
The CFPB advises consumers not to get close to their credit limits and notes that experts commonly recommend keeping credit utilization at no more than 30%. Some guidance suggests keeping it even lower.
You also do not need to carry a balance from month to month to build credit. Paying your credit card balance in full can help you avoid interest charges while maintaining responsible credit use.
3. Pay Down Existing Debt:
Reducing your outstanding credit card balances can help lower your credit utilization.
If you have several cards with balances, review your debts and create a realistic repayment plan. Avoid taking on additional debt simply to improve your credit score.
Remember that having a credit card does not mean you need to use the entire available limit. Keeping balances manageable can make it easier to maintain a healthy credit profile.
4. Avoid Applying for Too Much Credit:
Applying for several new credit cards or loans within a short period can affect your credit profile.
FICO considers new credit as one part of its scoring model, and multiple new accounts or credit applications may be viewed as a sign of increased financial risk, particularly if you have a short credit history.
Apply for new credit when you actually need it rather than opening accounts simply because a store or credit card company offers a promotion.
5. Keep Older Accounts Open When Appropriate:
The length of your credit history can also influence your score. FICO considers the age of your oldest account, your newest account and the average age of your accounts.
Therefore, think carefully before closing an old credit card, particularly if it has no annual fee and you can manage it responsibly.
However, keeping an account open is not always the right decision. Consider fees, account terms and your overall financial situation before making a decision.
6. Check Your Credit Reports for Errors:
Your credit report contains information that can be used to calculate your credit scores. Errors on your reports could potentially hurt your credit.
Review your reports for accounts that do not belong to you, incorrect payment information, incorrect balances, duplicate debts or accounts incorrectly listed as open or delinquent.
You can request your credit reports from the three major nationwide credit reporting companies: Equifax, Experian and TransUnion. Checking your own credit report does not hurt your credit score.
If you find inaccurate information, you can dispute it with the credit reporting company and the business that provided the information.
7. Build Credit With Responsible Accounts:
If you are new to credit or have a limited credit history, certain products may help establish a credit record.
For example, a secured credit card may be an option for some consumers who do not qualify for a traditional credit card. With a secured card, you generally provide a cash deposit that supports the credit limit.
The key is not simply having credit but demonstrating responsible repayment over time.
8. Be Patient and Consistent:
Improving your credit score is usually a long-term process. Accurate negative information cannot simply be removed because you want a higher score, and there is no secret shortcut that guarantees a rapid increase.
Focus on habits that you can maintain: pay bills on time, keep balances low, apply for credit only when necessary and regularly review your credit reports. Over time, responsible financial behavior can help create a stronger credit history.
Final Thoughts:
A good credit score is not built in a single month. It comes from consistently managing credit responsibly.
If you want to improve your credit score in the USA, start with the basics: pay on time, keep credit card balances low, avoid unnecessary applications, maintain a healthy credit history and check your credit reports for errors.
Small improvements in your financial habits today can potentially make borrowing more affordable in the future.